

Photo credit: Steff Hanson
The U.K. economy has been growing again. While this should theoretically be good news for workers, this time is different. Despite better economic momentum, the labor market has continued to lose jobs. Graduates and entry-level workers have suffered the most as companies have stopped hiring. The sectors that are contributing disproportionately to economic growth are tech and professional services, exactly where AI gains are expected to show up. Hospitality and retail have seen the highest job losses, driven by a surge in employment costs due to a significant payroll tax increase and successive minimum wage hikes under the Labour government. As a result, businesses have started to invest more again, automating some of the work that has become more costly. While higher economic output will benefit some workers, the jobless recovery is threatening to leave others behind.
GDP is growing despite headwinds
Since the first quarter of 2023, U.K. GDP has expanded by 3.6%. Economic momentum accelerated markedly this year, with annualized growth running at a rate of more than 2%, about twice as fast as last year. While the oil shock is now weighing on the outlook in the final quarter, economic growth has been significantly more robust than forecasters had anticipated in spring.
But despite this reasonably good performance, the job market has continued to suffer. Payroll employment has been on a downward trajectory since mid-2024, with some 250,000 jobs lost since then. This 24-month contraction is now the longest on record, even exceeding that of the Great Recession in terms of duration.
There are two economic trends that are mainly responsible for this jobless recovery: AI has started to boost output but not employment, while the large surge in employment costs has caused major job losses in retail and hospitality.
Productivity is rising in high-value-added services
Looking at which sectors are driving growth, we are starting to see signs that AI adoption is having an impact on the economy. Between 2019 and early 2026, output per hour increased by about 2.9% in the U.K. Excluding manufacturing, two sectors are the main driver of economic growth in the U.K., even as they only account for only a little over 15% of economic activity: information and communication (tech) and professional services. In fact, their growth contribution alone adds up to about 145% of the economy-wide gain, while most other sectors are net negative from a productivity standpoint.
The fact that two high-value-added industries, employing a large share of skilled white-collar workers, have accelerated in recent years is no coincidence. It is exactly what one would expect to happen as AI gets increasingly deployed: companies are producing more with the same number of workers. While this is boosting revenues, it’s also driving up compensation, at least for those workers who can successfully harness some of the productivity gains unleashed by AI.
Labor costs have surged
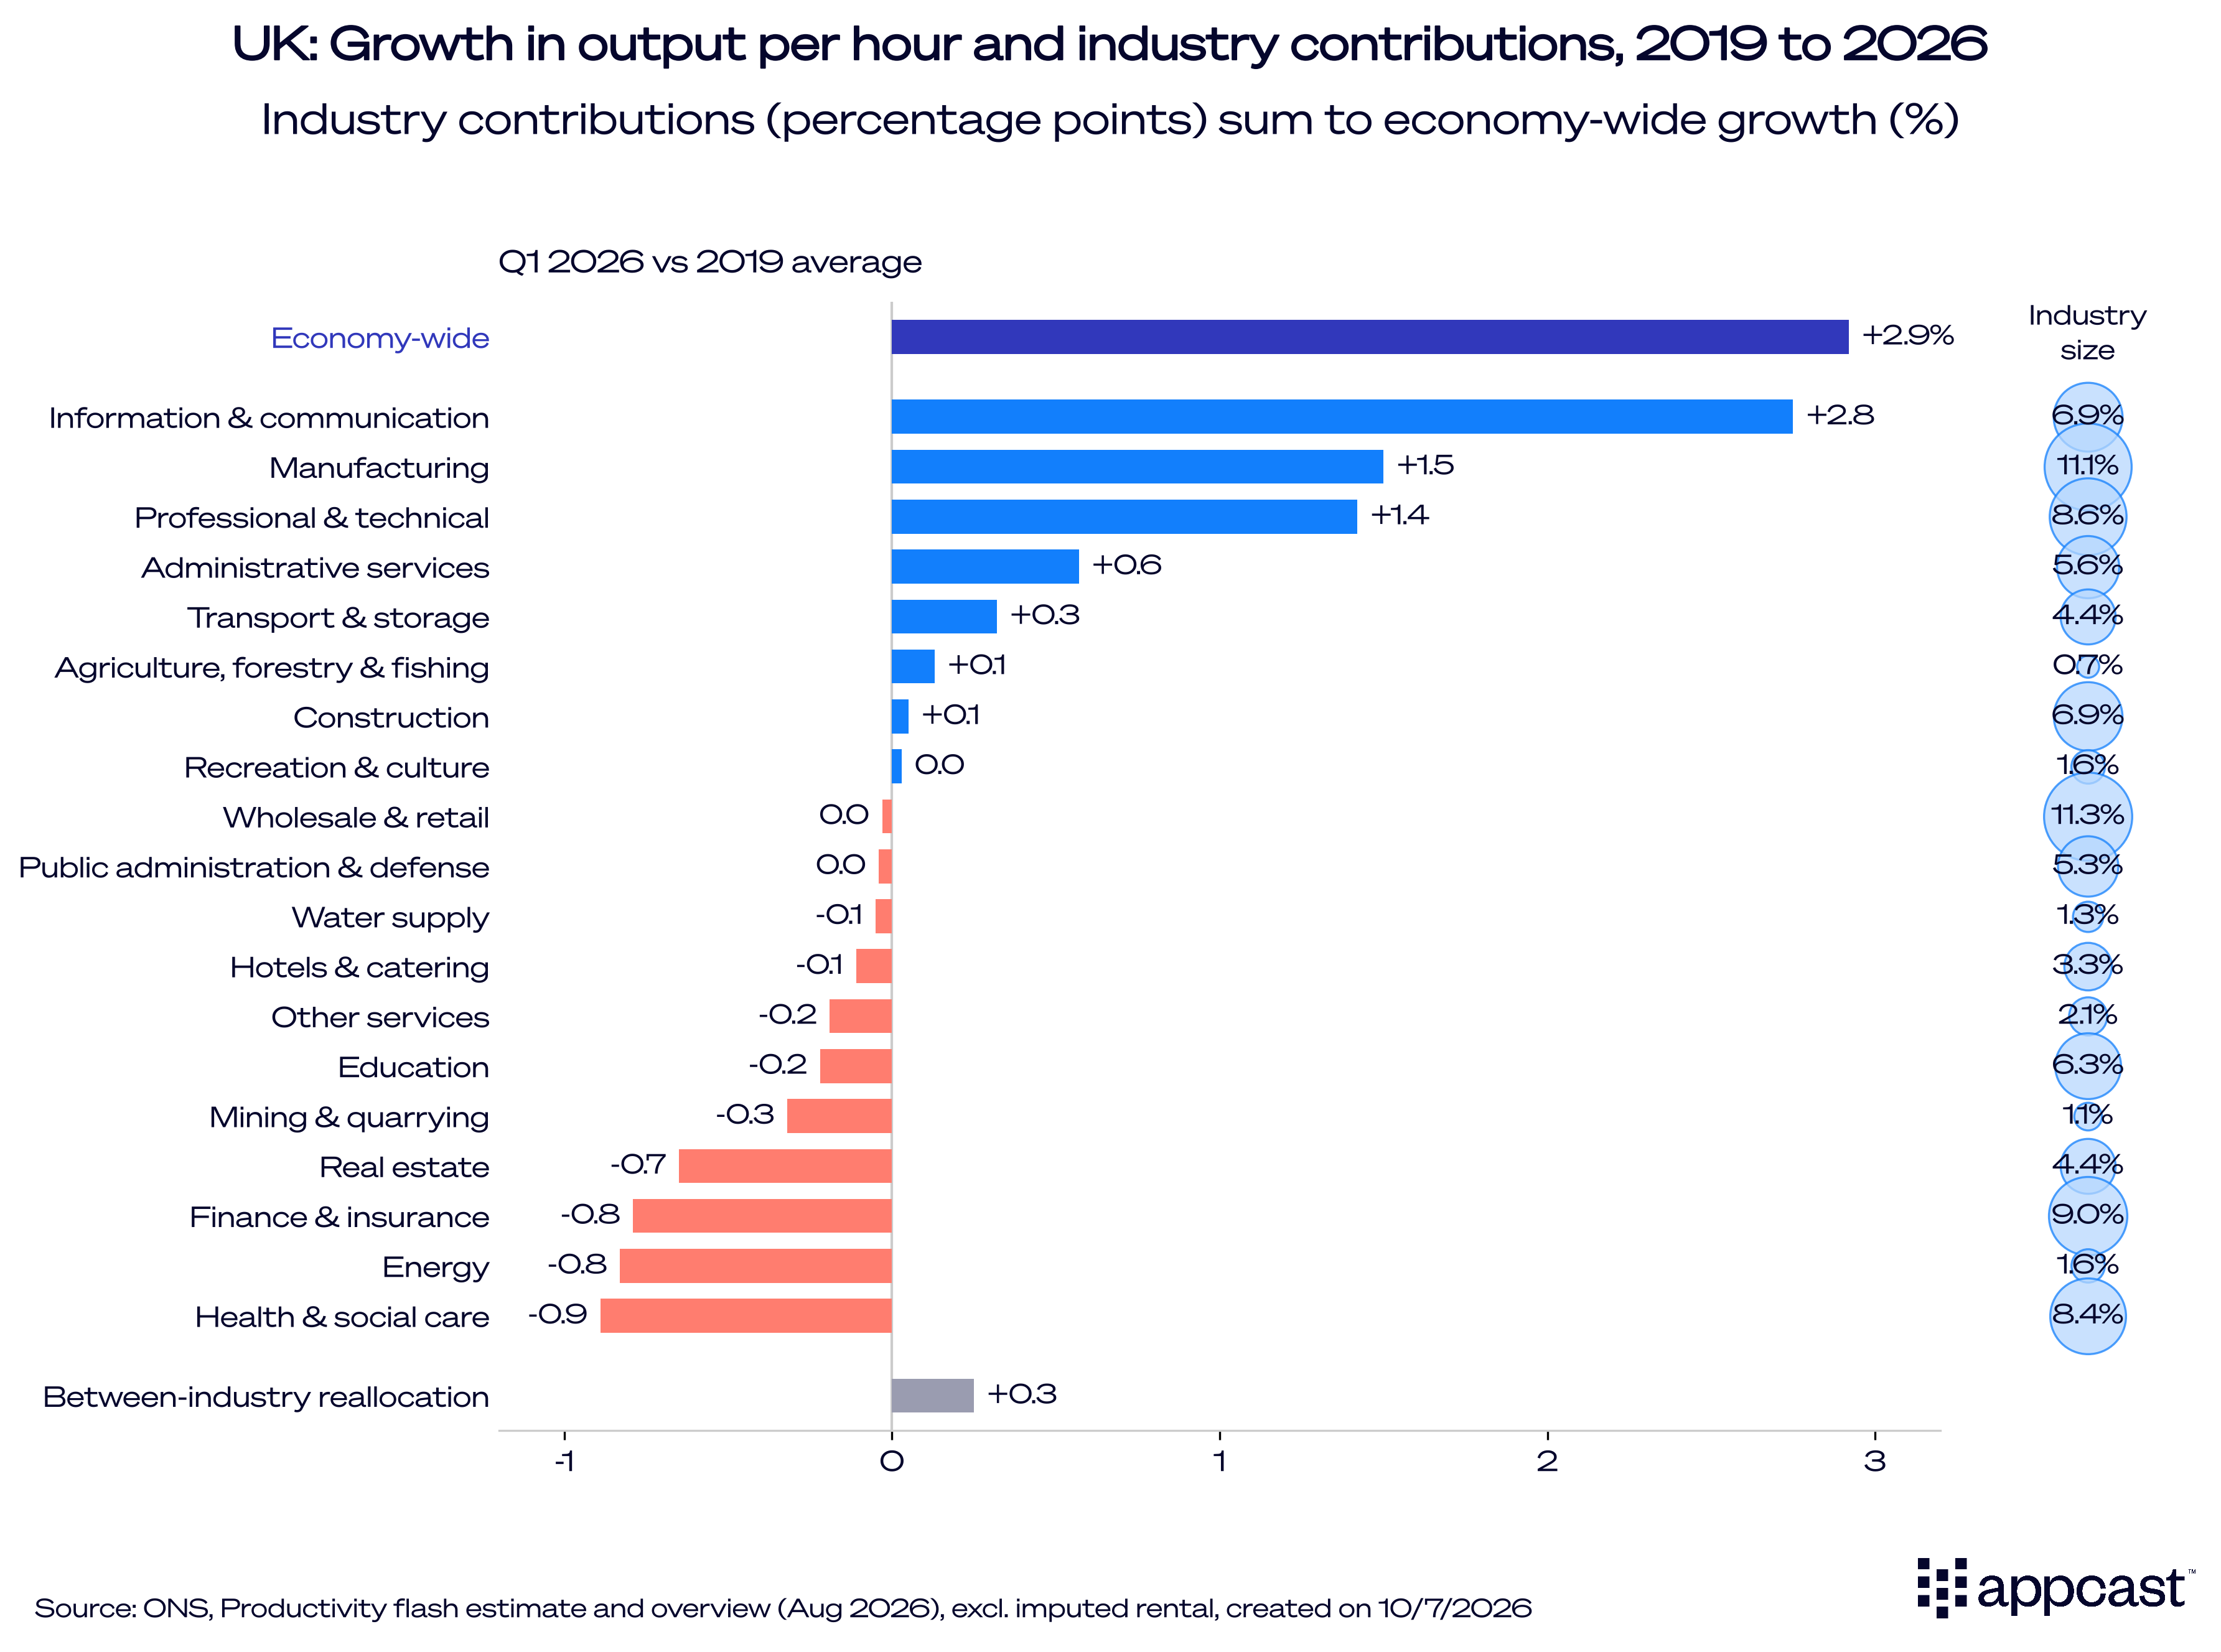
While AI might have caused a reduction in hiring across several white-collar occupations, it hasn’t been a main driver of job losses so far. For that, we need to look elsewhere. Economists at the Bank of England have identified the surge in employment costs that occurred under the Starmer government as one of the main factors driving the layoffs. Minimum wage hikes together with the large increase in National Insurance contributions turned out to be a toxic combination for employers who were already struggling amid a weak economic backdrop. OECD data shows that unit labor costs — a proxy for total employment costs that takes productivity into account — increased at a significantly faster pace in the U.K. than in other advanced economies between 2023 and 2026: There was a three-percentage-point gap between the U.S. and U.K. for several years. While it has narrowed more recently, forecasts expect U.K. labor costs to grow faster than those in other countries in the years to come. It is this extreme surge that can explain why the layoffs have predominantly affected low-margin industries like retail and hospitality, where many employers could not keep up with the rising wage bill.
Businesses are investing more, automating work
Business investment in the U.K. was stagnant for the better part of the decade following Brexit but has now risen by more than 7% in inflation-adjusted terms since 2024. Undoubtedly, employers are using technology to bring down wage bills. While a greater push toward automation increases efficiency and drives productivity gains, which will be good for the economy in the long run, this is probably not exactly what the government had in mind when pushing through its minimum wage agenda. Researchers and policymakers agree that the U.K.’s wage floor — one of the highest in the world — is now exerting an economic toll, which overwhelmingly falls on the young and less affluent as their labor market prospects have deteriorated the most. Youth unemployment is now at its highest level in more than a decade.
What does this mean for recruiters?
For several years following Brexit, the U.K. economy had a capital problem. Neither the business sector nor the public sector was investing enough, causing economic stagnation even as the labor market was close to full employment. Now, the U.K. has a labor problem. The private sector is investing again, and AI is contributing to significant productivity gains in high-value-added services. This is boosting output, but it hasn’t created many jobs. Moreover, companies have started to automate work in response to the surge in labor costs, leading to substantial job losses across sectors, with retail and hospitality affected the most. The economy has shifted to a new equilibrium with more capital and less labor because of technological trends and taxation. While the British case is extreme, other countries, such as the U.S., have also seen their labor markets weaken even as AI-driven growth has boosted GDP and productivity.
For recruiters, this means that the current hiring drought might reverse only slowly, especially as global uncertainty remains a concern. Companies will continue to be cautious and cost-conscious in their hiring approach. There are two pockets of the labor market where we expect hiring competition to be fiercer, and both are related to the AI economy. First, the data center construction boom and rising energy needs are creating higher demand for skilled trades. Second, the demand for workers with AI skills in professional services and tech is soaring. As talent supply hasn’t kept up, expect rising compensation in that space.