

Photo credit: Sasun Bughdaryan
Inflation is rising again due to surging energy prices, and central banks are responding. The European Central Bank (ECB) has led the pack, raising rates twice this year, while the Federal Reserve (Fed) hiked once in September and the Bank of England (BoE) followed today. At the press conference, Governor Andrew Bailey signaled that another interest rate increase is probably unavoidable unless the outlook improves dramatically. Although tighter monetary policy is warranted to contain inflation, both households and businesses will have to prepare for higher costs due to a combination of rising prices and less affordable credit. This is concerning because real wage growth has also turned negative again. While the labor market impact has been limited so far, some sectors will feel the pain more than others.
The outlook: Higher prices mean higher interest rates
Most of the inflationary pressures that are in the pipeline are due to rising energy prices, caused by the ongoing conflict with Iran and the war in Ukraine. Even with yesterday’s steep fall following the midterms, oil prices remain highly elevated relative to one year ago.
Household energy costs have already surged — in some countries, like the U.K., prices are capped — but even there, the price shock is set to arrive this winter. Inflation rates have already responded this fall, surging to 4% in the Eurozone, with the U.K. not far behind. And forecasters expect that we haven’t reached the peak yet. The U.K. seems to be particularly exposed, with inflation potentially rising all the way to 5% again by next April.
It is thus no wonder central bankers fear that higher energy prices are already contributing to price and wage pressures across the economy. If these forces strengthen, it would become even more difficult to contain inflation.
Economic growth has actually been stronger than most forecasters anticipated, especially in the U.K. and the Eurozone. The reason: AI has been boosting growth thanks to the data center construction boom as well as higher output in tech and professional services. Labor markets have been holding up better than expected, too. This strengthens the case for raising interest rates. Typically, central bankers try to avoid hiking into a recession when faced with adverse supply shocks.
With economic activity resilient, financial markets expect a globally synchronized interest rate surge as central banks attempt to fight inflation. The ECB is expected to raise rates up to three more times, bringing its key rate to 3.25%, while policy rates in the U.K. and the U.S. could reach about 4.5% by next summer.
Households are being squeezed
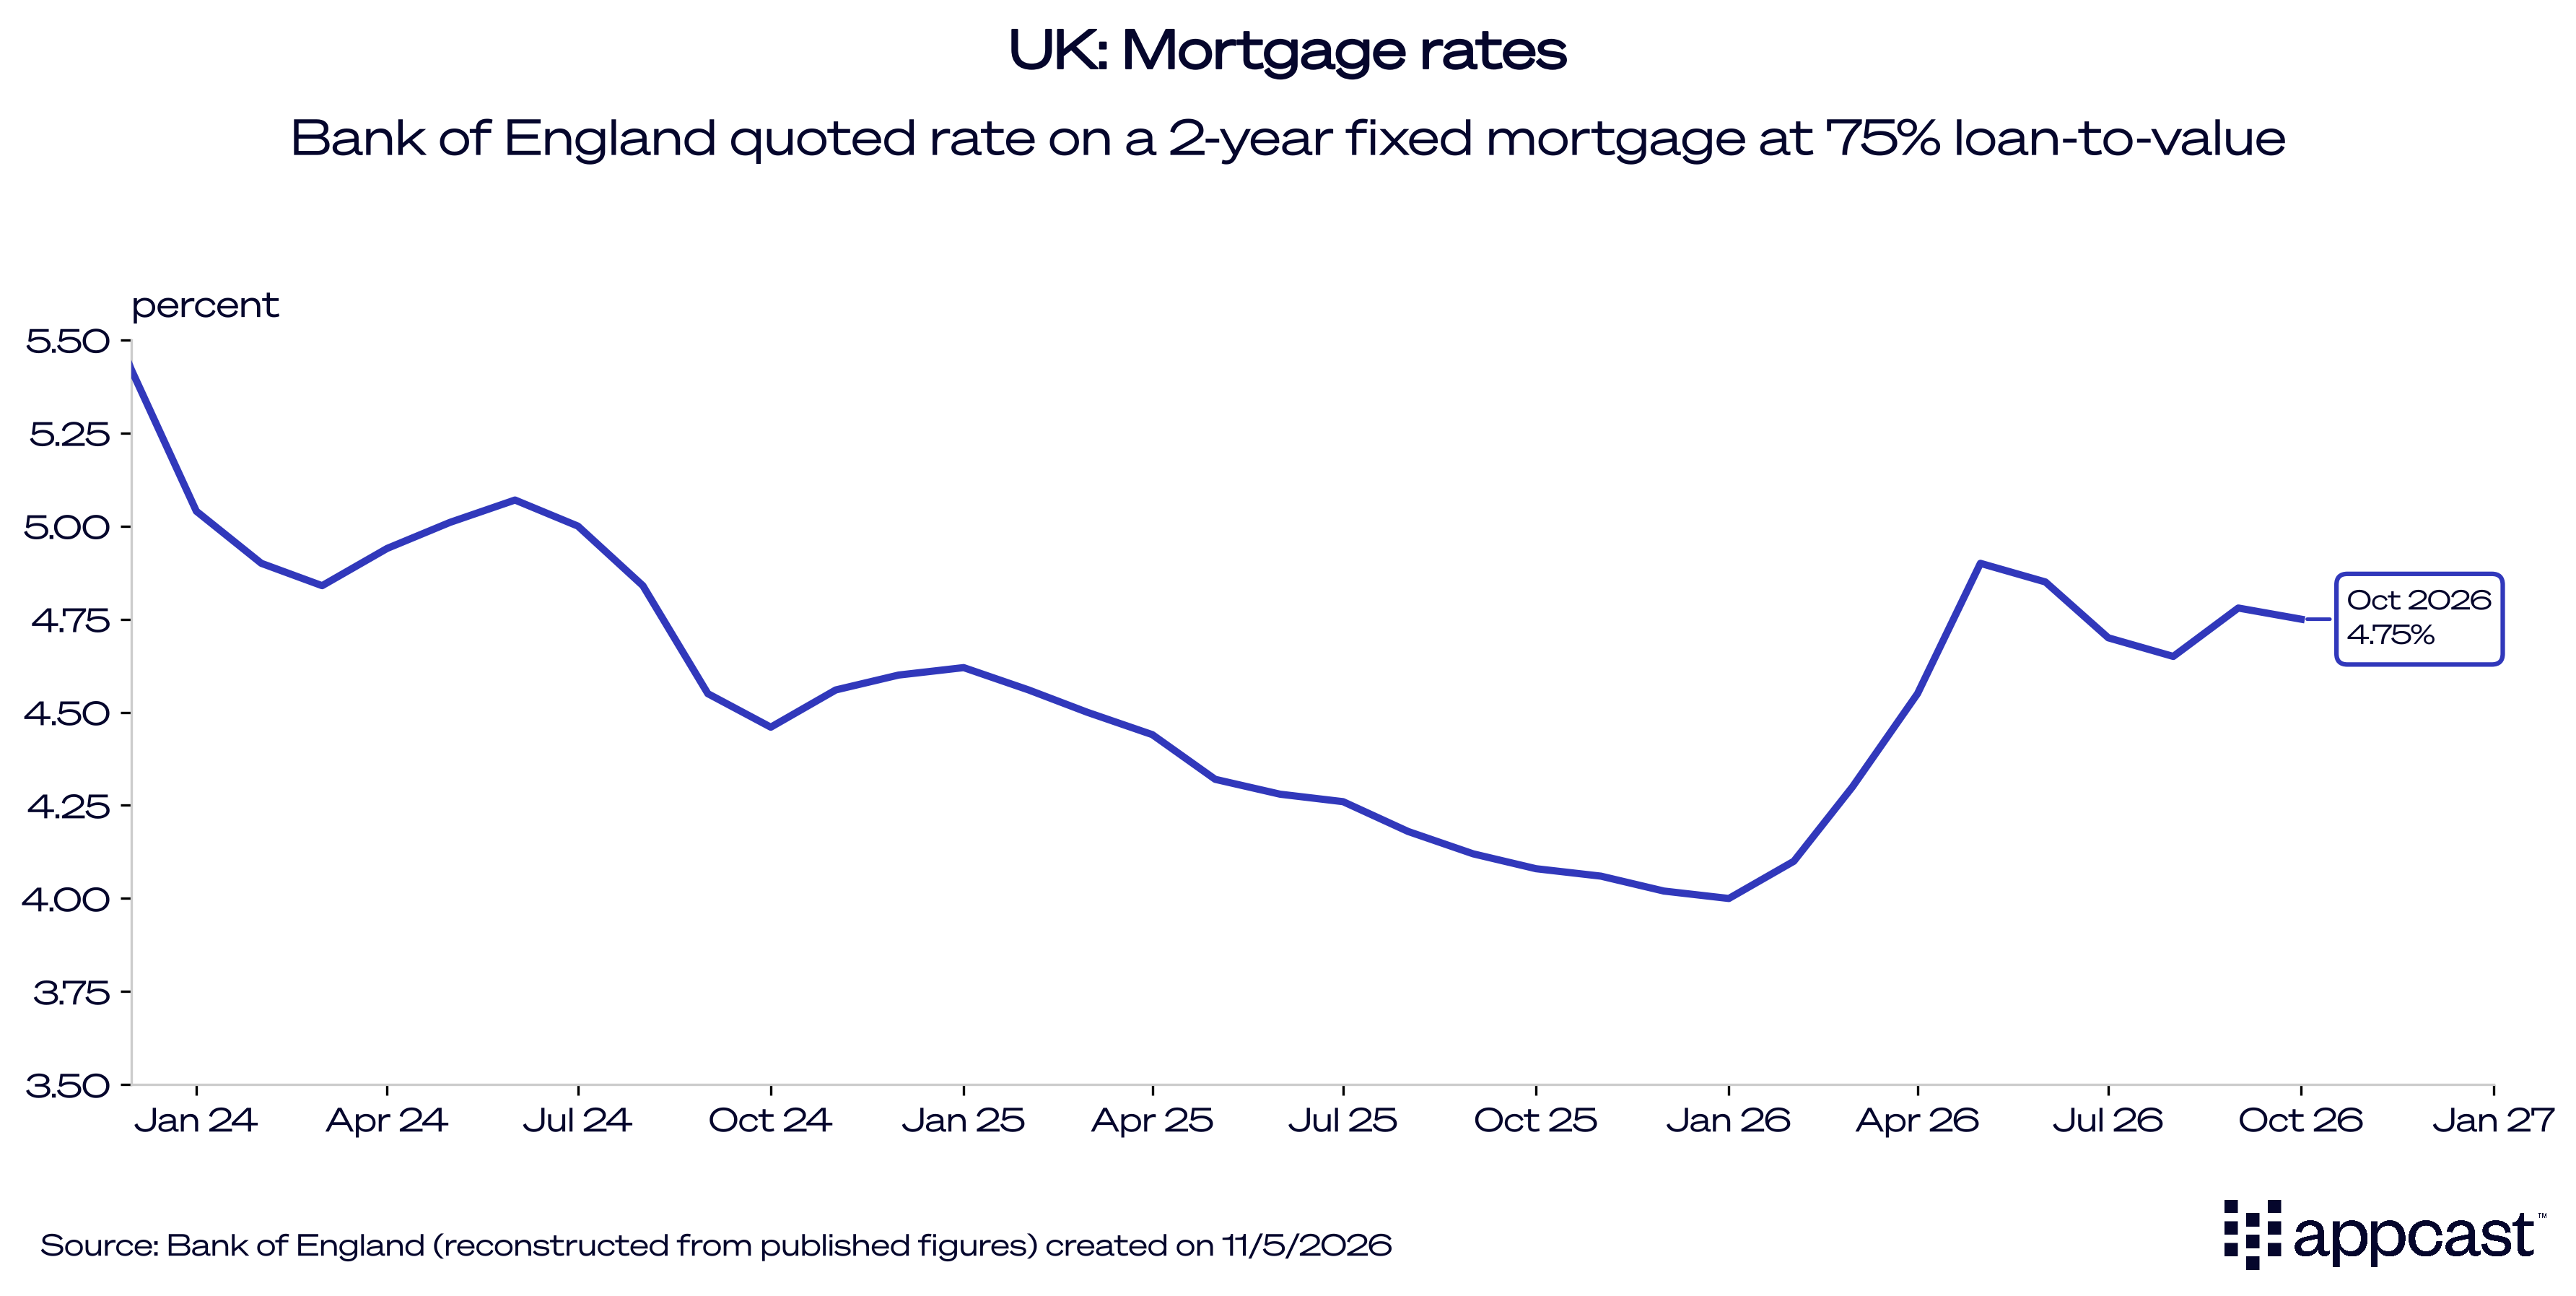
Both households and businesses will therefore face a double whammy: rising prices due to the energy price shock combined with higher interest rates. The second effect, in particular, will have more pronounced distributional consequences. Higher rates are bad for debtors. They also negatively affect the housing market because mortgages become significantly more expensive. Two-year fixed rates in the U.K., for example, have already risen by about 0.75 percentage points since January. Existing property owners are often protected because their rate is locked in, at least in countries such as the U.S. or Germany, where long-term mortgages are common. But even there, higher rates create a lock-in effect in the housing market. In the U.K., mortgages are typically fixed for only two or five years, or are variable altogether. This means that the current interest rate shock will lead to significantly higher mortgage costs for millions of households in the years to come.
How the labor market responds
While the labor market has been somewhat resilient, it is not immune to higher interest rates. Tighter monetary policy in response to the price shock simply means less overall demand in the economy. But as we’ve explained previously, the effects are not evenly distributed. Some sectors and occupations are more exposed to interest rate shocks than others. As it turns out, not many studies have examined this particular issue. Interest rates rarely move on their own but are usually a response to other macroeconomic variables changing as well. It is therefore not easy to disentangle how much of the employment shock is because of changing interest rates and how much is due to other factors.
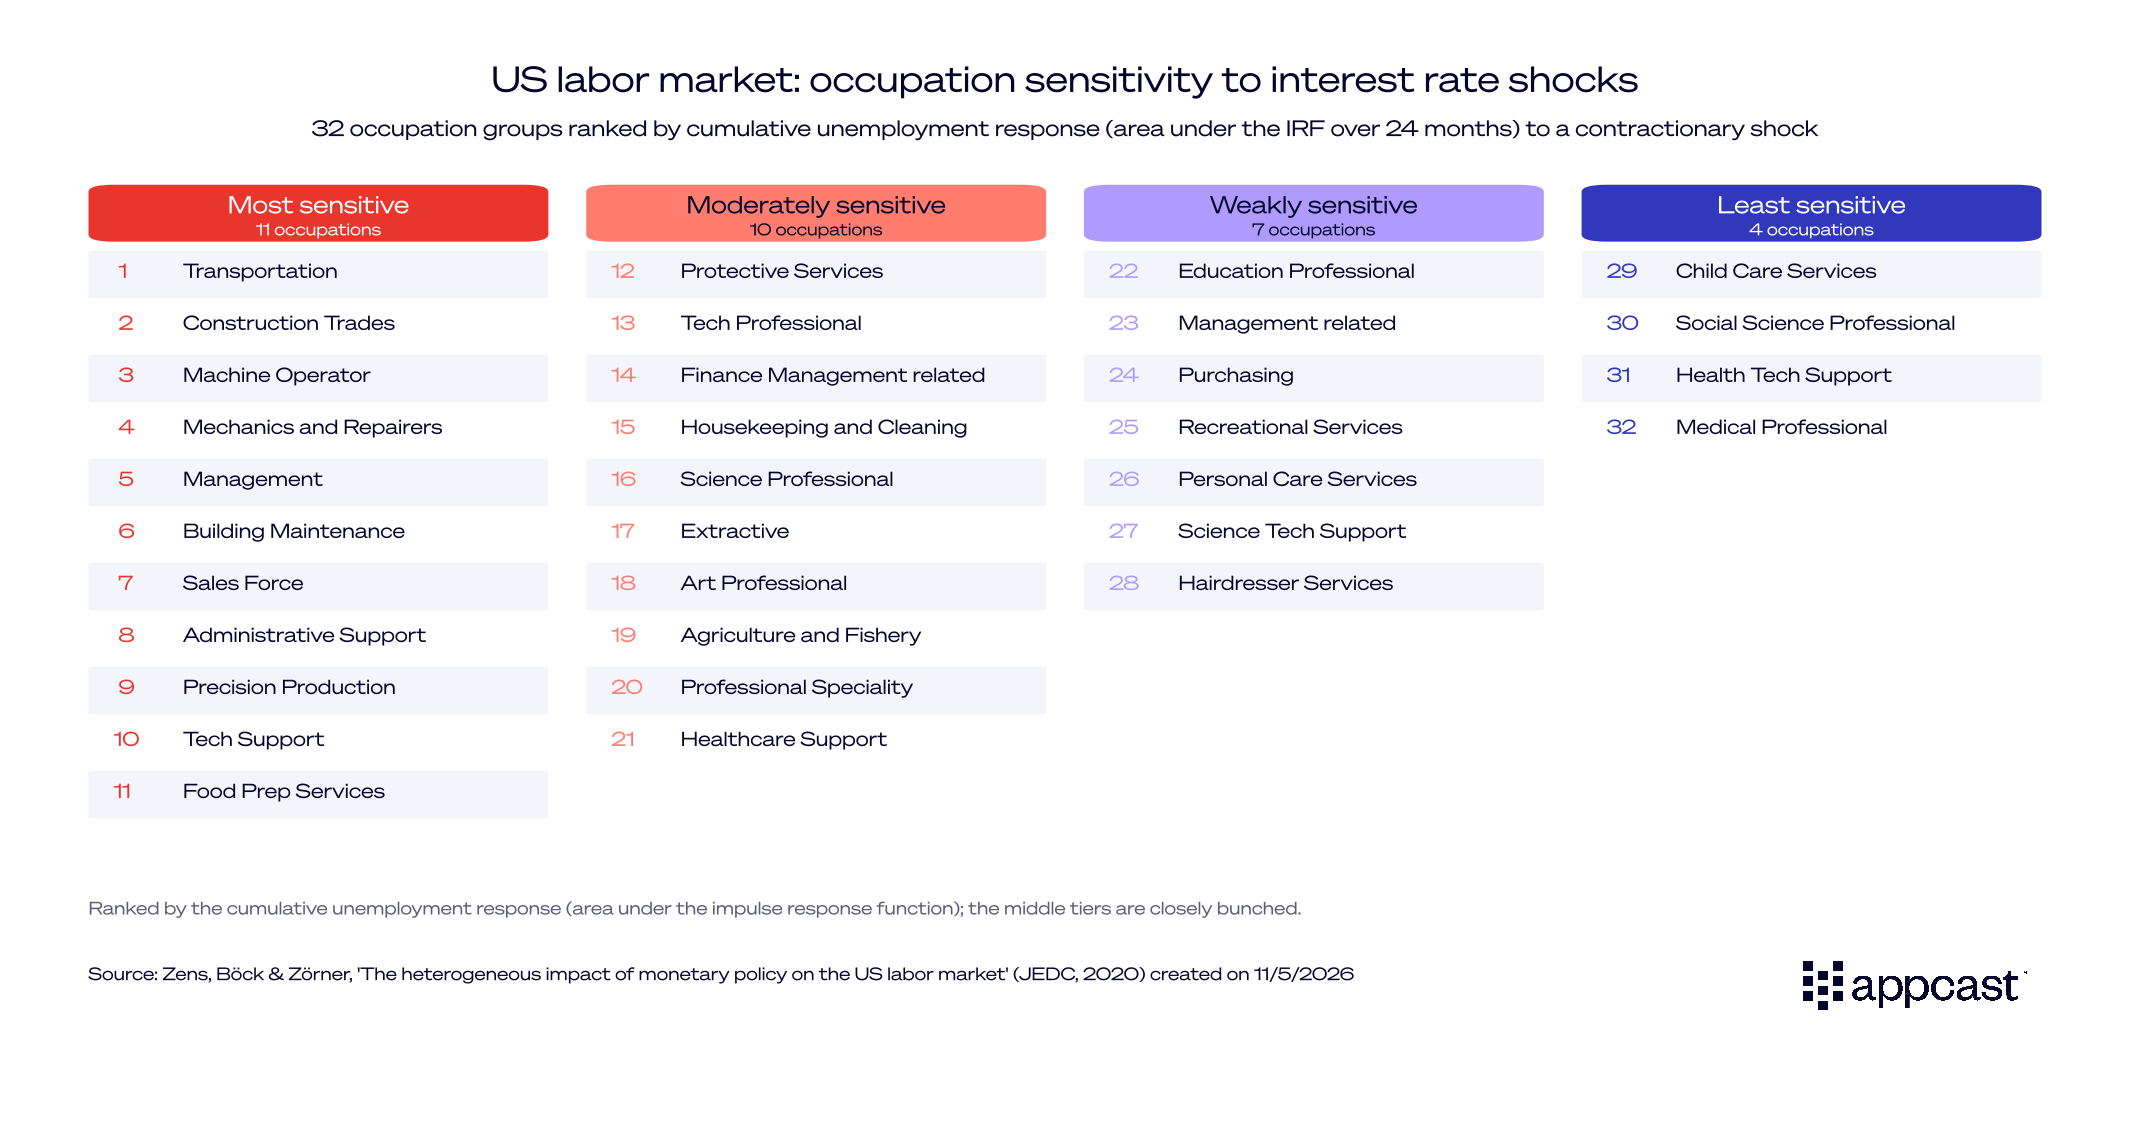
Nevertheless, one economic study attempted to do just that, showing the uneven impact of a monetary policy shock across 32 occupation groups. While the research focuses on the U.S. labor market, its findings likely apply to similar economies as well. The authors’ results are summarized in the table below, which ranks them by interest rate exposure. Health, medical, and childcare professions are the least affected. This makes sense. Spending on these services does not move too much with the business cycle. The same is true for educational professions, personal care, and science and tech support, all of which are only weakly sensitive. Tech and finance professionals, together with housekeeping services, are moderately sensitive.
The occupations most exposed to interest rate shocks are relatively large occupational groups, making up a significant share of the labor market. Transportation and construction trades together with mechanics and food preparation are all highly exposed to the interest rate shock. What is striking is that these groups typically also include a large share of low-skill workers. The main finding of the paper is that monetary policy shocks disproportionately hurt workers at the bottom of the skill distribution because their labor market prospects worsen significantly, while white-collar workers are generally more insulated.
What does this mean for recruiters?
For now, labor markets are holding up OK even as interest rates are projected to increase. This makes sense. Central banks are not aiming to create a recession but merely to contain inflation. Nevertheless, absent an improvement on the energy price front, they can only reduce inflation via lower demand. Households’ living standards will deteriorate with prices growing faster than wages, while higher rates lead to additional cost pressures.
Hiring is not immune to rising rates either, and the effect depends on the sector. Some occupation groups like healthcare and childcare will barely respond, while others are significantly more exposed to cyclical factors. High-skill professions are more insulated — but not always. Low-skill workers are typically more exposed, as many are employed in retail, hospitality, and construction, all of which respond more forcefully to lower demand. Expect a sharper decline in recruitment for any of these groups as rising interest rates curb economic activity.