

Photo credit: Eduard Pretsi
The new Burnham government announced a range of economic policies in its Budget on Wednesday — the U.K.’s annual fiscal event. This piece summarizes some of the key measures together with an assessment of what they mean for the economy and labor market.
The economic backdrop
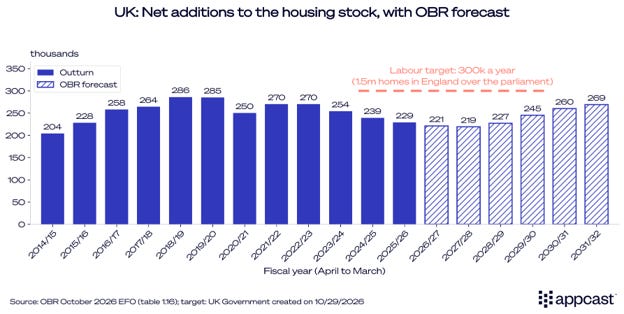
Even with growth surprising on the upside recently, the U.K. economy is in a pickle. Public finances are under severe strain. Interest rates are at their highest in almost 20 years. The government now spends more on debt interest than on defense — about £120 billion a year. House building has plummeted because construction costs are soaring, making Labour’s promise to build 1.5 million units by 2029 nothing more than a pipe dream. Payroll employment has contracted by more than 170,000 over the last two years. Youth unemployment is at its highest in more than a decade. Workers are stuck in their current roles as the labor market has frozen, with policies like the Employment Rights Bill actively contributing to the slow hiring environment. Regulation and excessive taxation are strangling the economy, with some employees deciding to cut work hours because of high marginal tax rates. With current policies effectively rationing land, capital, energy, and labor, one might wonder how there is growth at all.
Some key announcements of the Labour Budget
So what did the Labour government actually decide on?
Policy: Household energy subsidies
Households in council tax bands A to D will be given a £100 energy payment, while gas standing charges are scrapped. The cut in fuel duty is extended.
Assessment: Good news for about 20 million households, but the subsidy is an extremely poorly targeted measure. Remember that the council tax bands are based on property valuations made 35 years ago. There is also a geographic skew. Many households in the South East of England and close to half in London will miss out. While a £100 cash boost is always welcome, estimates suggest that households’ annual energy bills are set to rise by several times as much due to surging energy prices (an increase of 25%). With the elimination of the standing charge, gas bills will be more closely linked to consumption. Meanwhile, fuel at the pump will remain 5p cheaper until July.
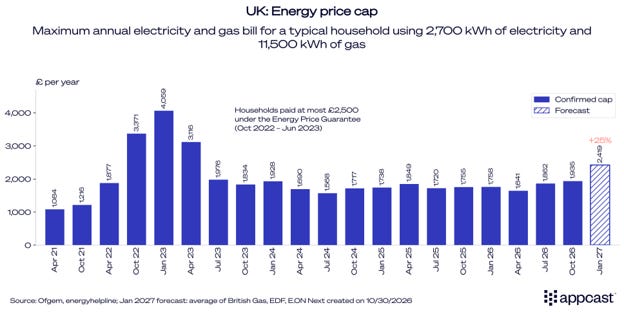
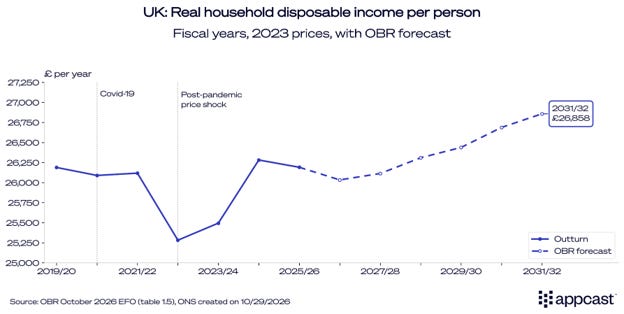
As a result of the energy price shock, though, household disposable income is projected to fall until early 2028, leaving households no better off than before the pandemic. In other words, almost a decade of stagnation.
Policy: Pensions
The triple lock is adjusted, but only after the end of this parliament.
Assessment: Under the current triple lock, state pensions rise by whichever is highest: inflation, earnings growth, or 2.5%. If this unsustainable policy were to continue indefinitely, pension commitments would eventually swallow the entire economy. With the adjustment, pensions will only grow by 2.5% or inflation, while keeping their average value in line with long-run wage growth, a weakened triple lock, if you will. While this adjustment is necessary, it only kicks in from 2030 — another example of how backloaded Labour’s potential savings are.
Policy: Minimum wage increase
All hourly minimum wage rates increase by about 3.9% next April.
Age 21 and above (National Living Wage): £13.21 (previously £12.71)
Ages 18–20: £11.27 (previously £10.85)
Ages 16–17 and apprentices (under 19 or in their first year): £8.31 (previously £8.00)
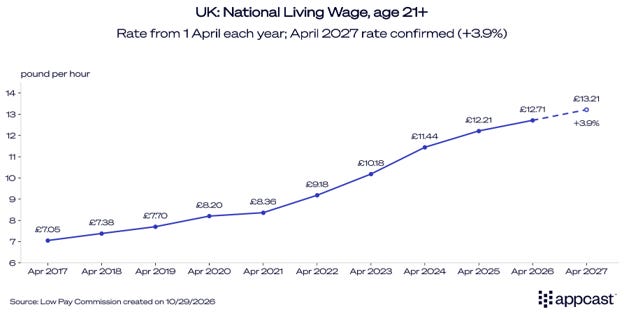
Assessment: For the first time in years, minimum wages are increasing at a slightly lower rate than median pay, but just barely. The U.K. now has one of the highest, maybe even the highest, wage floors relative to median pay. This has created massive wage compression at the bottom, with perverse incentive effects for workers — why take on more responsibility if it doesn’t pay? — and it has also contributed to the hiring crisis, with small businesses being squeezed by soaring labor costs. A more benign hike is a much-needed adjustment for the labor market.
Policy: Visa changes
The government is keeping the graduate visa at two years for universities with strong track records, reversing a planned cut to 18 months. It is also making it easier for skilled workers to change jobs: The highest-paid will get up to six months, rather than 60 days, to find a new employer.
Assessment: Both of these are good policies. The U.K. needs more skilled immigrants, not fewer. Letting graduates stay longer is the right approach. I also strongly support the changes to the skilled worker visa. When I was looking for a new job more than three years ago while on that visa myself, it turned out to be a substantial barrier. Switching jobs requires a new sponsor, and workers who lose their job have just 60 days to find one. This lock-in effect keeps workers from moving to better opportunities, which hurts labor market fluidity and, ultimately, economic growth.
Policy: Subsidies for first-time buyers
First-time buyers can purchase a new-build home with a deposit of only 2.5%, backed by a government loan covering 20% of the price.
Assessment: As a U.K. homeowner myself, I say “thank you,” but as an economist, I say “no, thanks!” This is yet another instance of a government subsidizing demand for homes rather than helping out with the supply side. According to estimates, the U.K. is short by about six million housing units. The only way to improve affordability is to address this chronic housing shortage, yet the government will fail to reach its housing target by a mile. Giving handouts to first-time buyers boosts prices but does little to address affordability. And it also increases financial stability risks.
Policy: Higher taxes on savings and rental income
Tax rates on savings and property income rise by a further 2 percentage points, while the planned cut to the £20,000 cash ISA allowance is scrapped.
Assessment: This penalizes savers and landlords. While the former can stash their money in a tax-exempt cash ISA, landlords have little recourse. Higher interest rates, together with the hassles of the Renters’ Rights Act, have already led to a large decline in the supply of rental units, as landlords decided to sell. The obvious outcome: Rents are rising at a faster rate than inflation, putting additional pressure on living costs. And higher taxes will worsen the situation.
These are just a few of the nearly 100 measures announced (full list here). From a macroeconomic viewpoint, most are piecemeal tweaks too small to move the needle.
What does this mean for recruiters?
The good news is that the new Labour government delivered a no-harm Budget: Financial markets reacted calmly. After two years of significant tax hikes under Rachel Reeves, which hurt the economy, Chancellor Healey opted for a more timid approach, with more benign tax increases and spending commitments. Most of the policies will do little either way for growth or the labor market.
But that is also the bad news. The U.K. — stuck in a low-growth environment, strangled by regulation and high public debt — faces enormous challenges that need to be addressed now. One would have hoped that, after one prime minister was pushed out, Labour would grasp the seriousness of the situation. Think again! This week’s Budget postpones critical decisions once more, hoping the economic outlook and fiscal position will simply improve on their own. But hope is not a strategy. Like previous Tory governments, Labour is kicking the can down the road.
From a recruitment perspective, all of this was a little bit of a snooze fest. Expect hiring to stay cautious at least until early next year. None of the policies will seriously harm the outlook, but there was also very little substance in there that could improve the labor market. A missed opportunity!