

Following one month of positive news, the latest U.K. labor market data continues to underwhelm. Payroll employment in October contracted by more than 30,000, with job losses concentrated in a single sector — retail — and vacancies continuing to decline. While the unemployment rate showed an unusually large decline, it is based on the less reliable household survey, meaning that data quality is a concern. Nominal wage growth remains unchanged. But with inflation rising, real pay growth is falling and heading toward zero.
Job losses remain heavily concentrated in blue-collar sectors
Following a gain of about 20,000 jobs in September — the first positive reading in more than half a year — job growth turned negative again in October. The preliminary data shows a loss of about 34,000. While recent data tends to slightly overstate job losses at first, it would take a significant data revision for the October number to turn positive, which we think is unlikely. The U.K. labor market therefore continues to shed jobs, albeit at a slow pace of about 10,000 per month on a six-month rolling basis, and has been doing so for about two years.
While many of you might now believe that this is due to AI, the data is very clear: Job losses are heavily concentrated in blue-collar sectors with very little AI exposure. As we have discussed on multiple occasions, domestic policies that have led to a surge in employment costs are the reason. The two main culprits are tax hikes — the increase in employer National Insurance contributions (NICs) — and the relentless annual upward creep of the minimum wage.
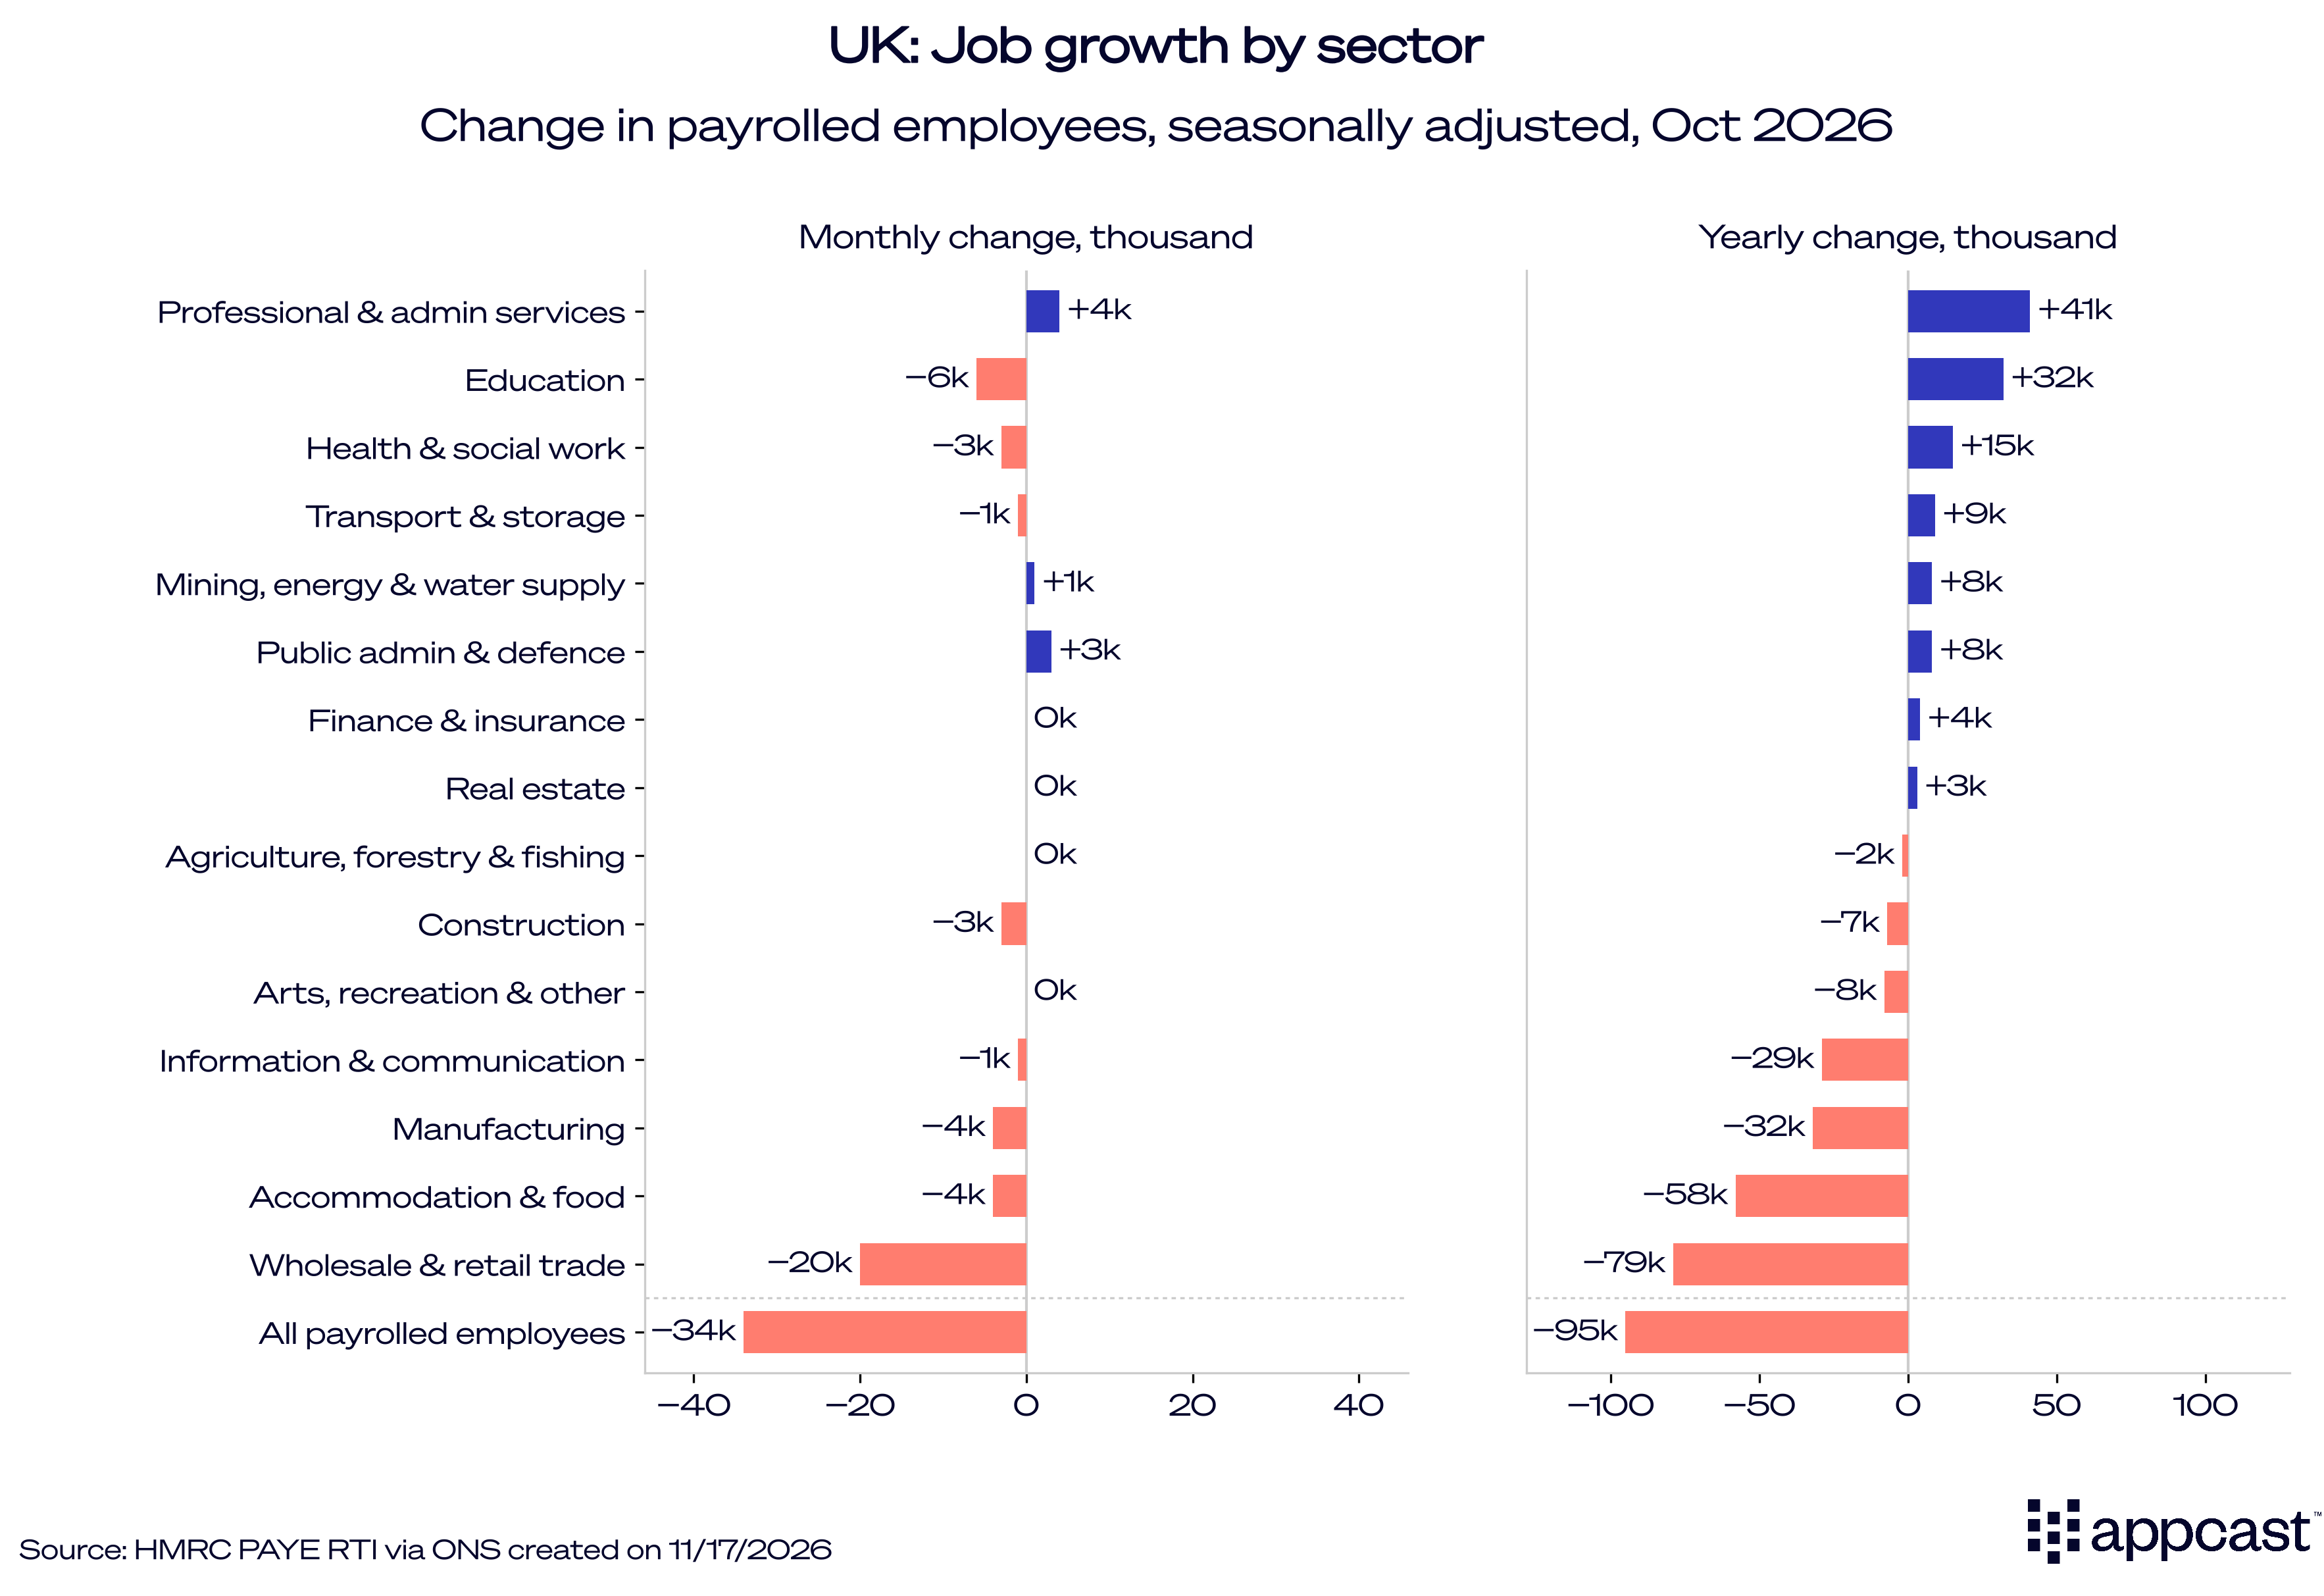
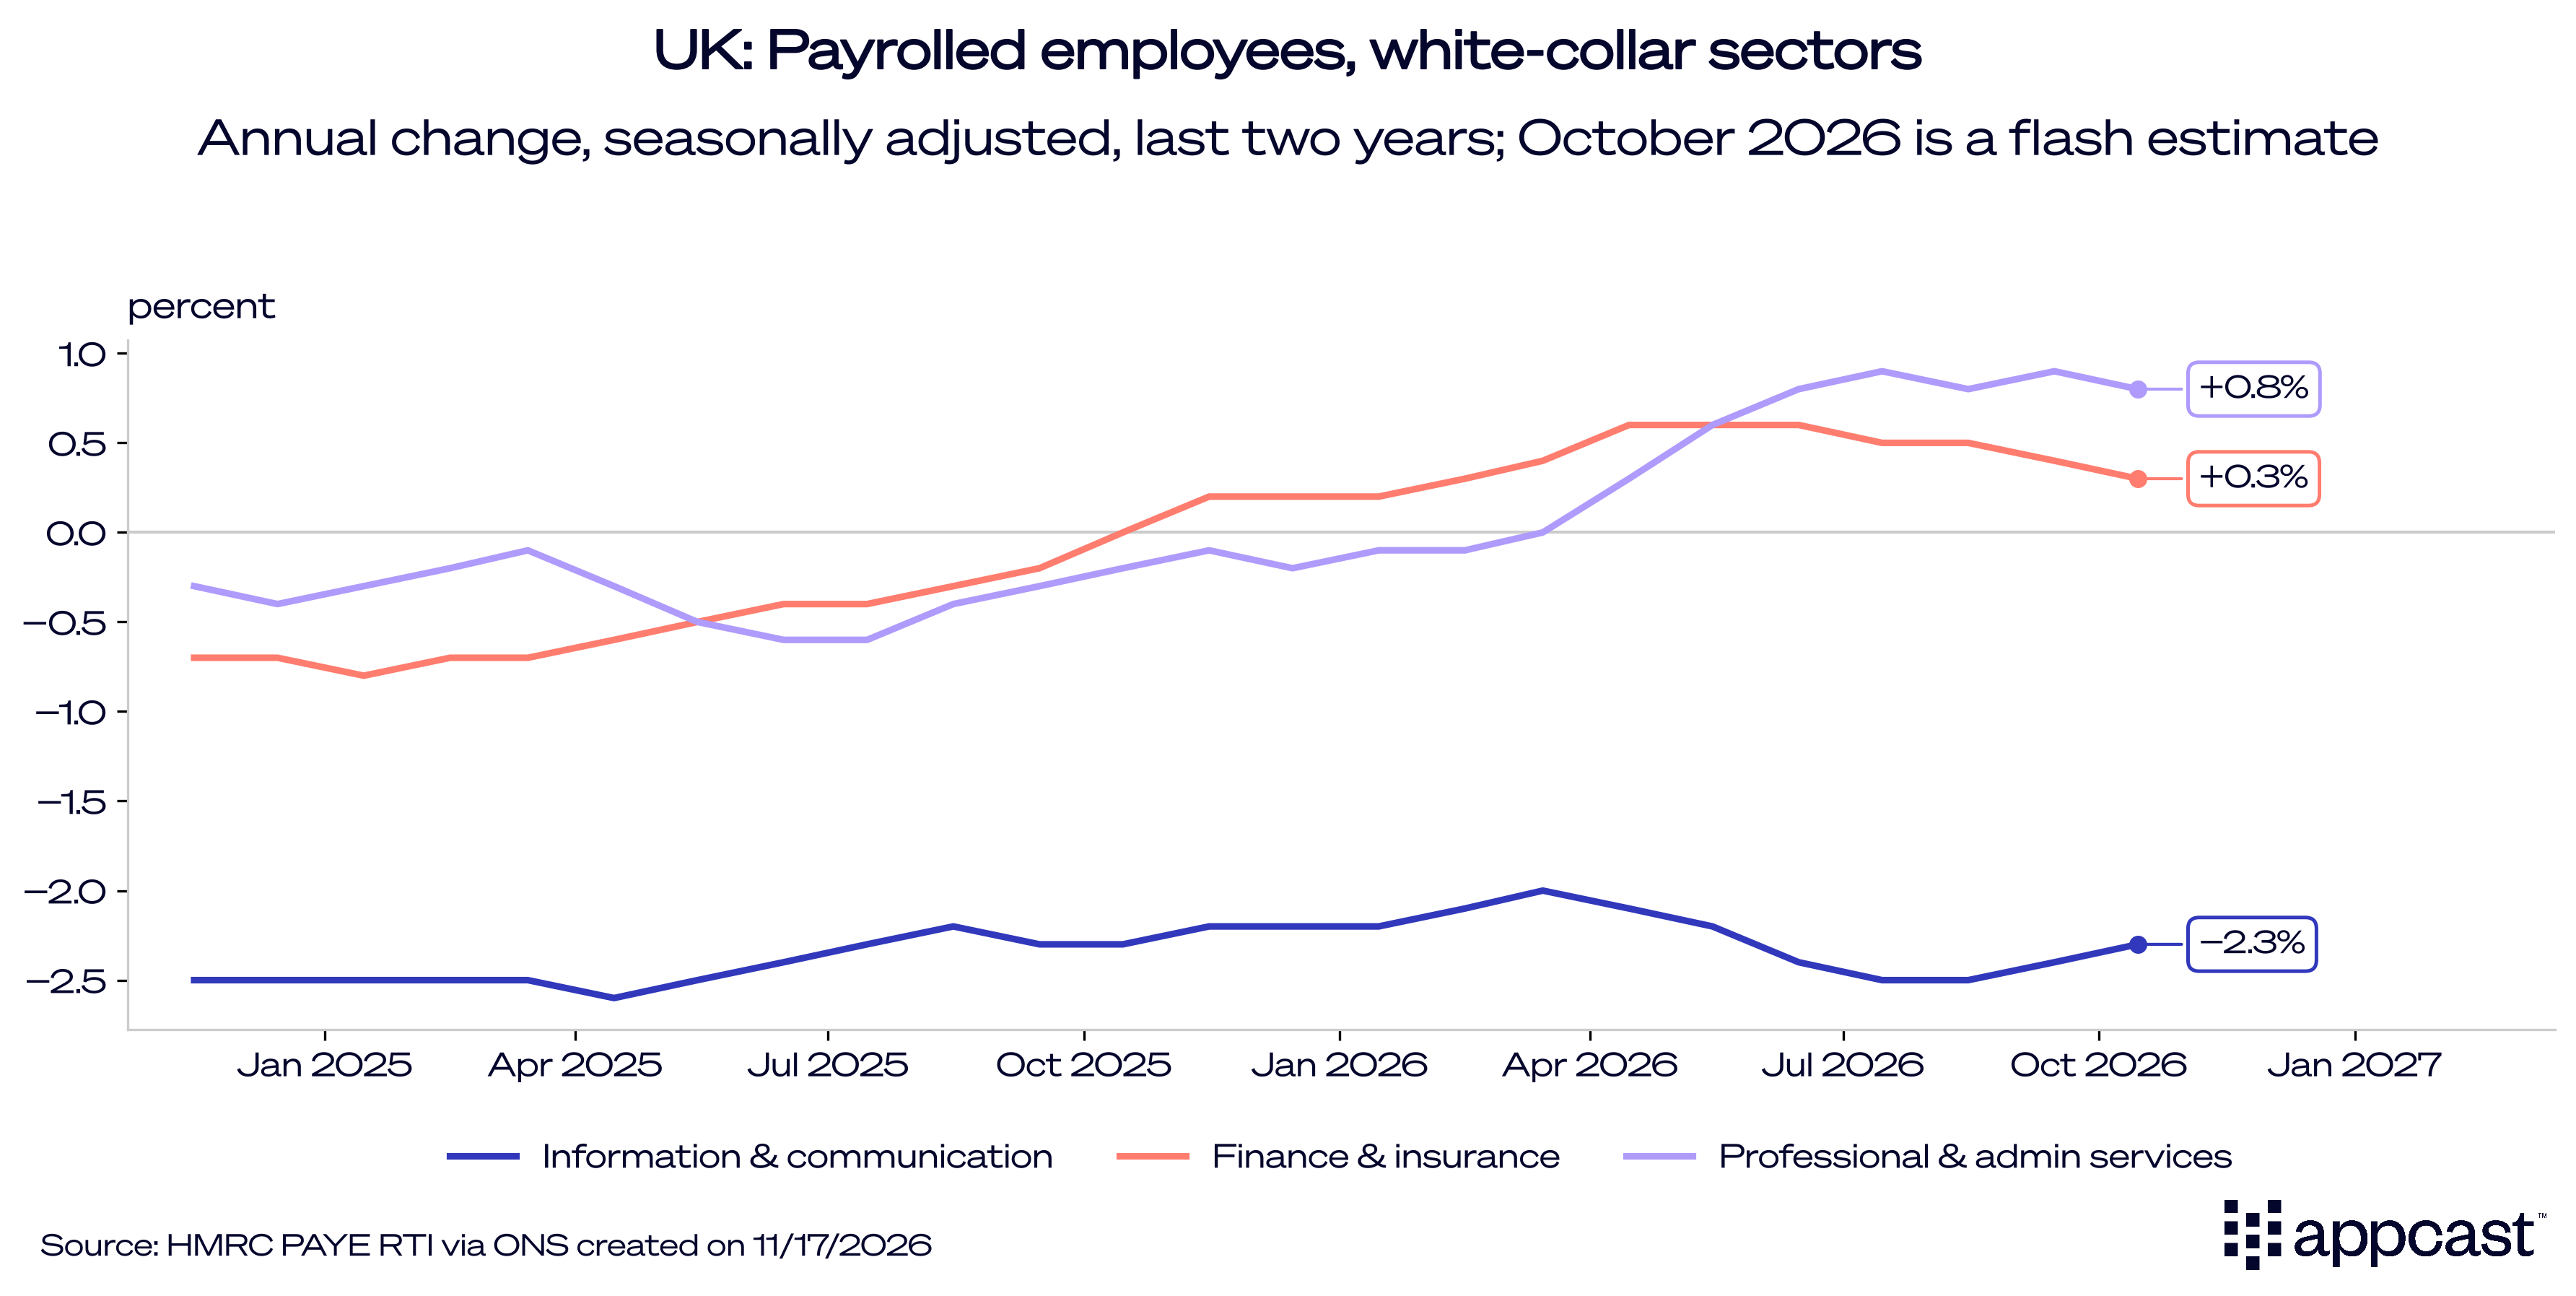
As a result of these policies, low-margin sectors where employment costs are a major input have accounted for the biggest share of recent job losses. Over the last year, about 80,000 jobs have been lost in wholesale and retail, another 60,000 jobs in accommodation and food services, and 30,000 in manufacturing. While tech employment also declined by about 30,000, professional and administrative services compensated in the white-collar space by adding about 40,000 jobs. Healthcare and education have also created jobs.
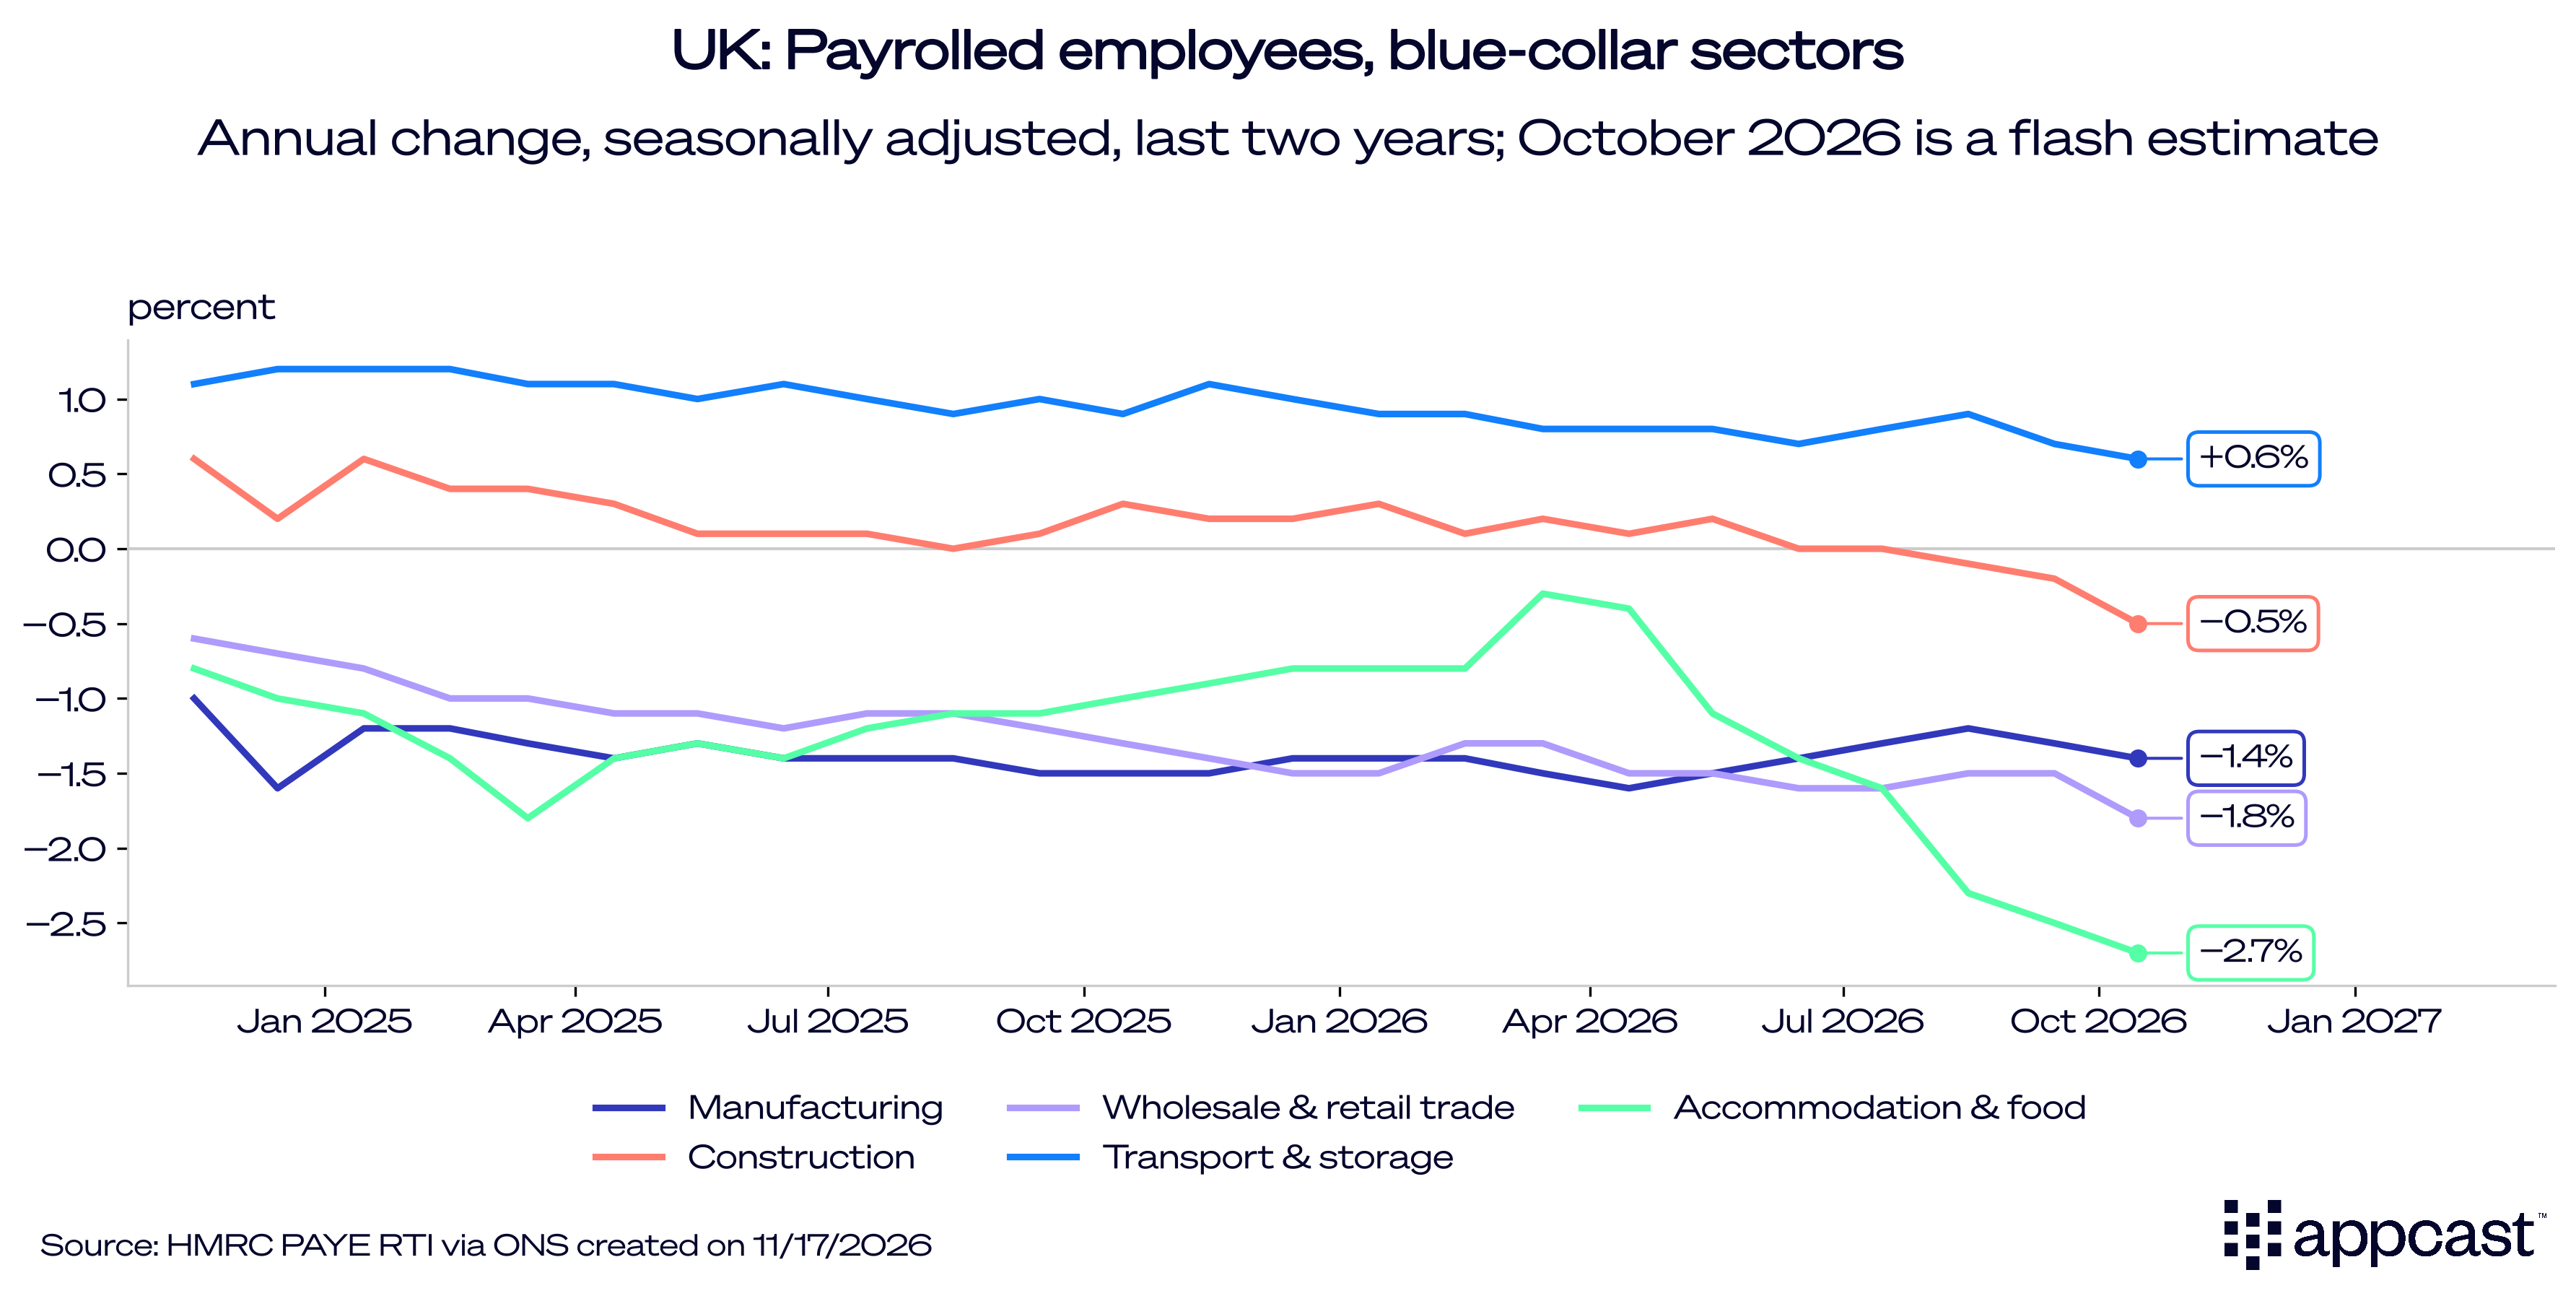
There is thus a relatively clear dividing line between low-skill and high-skill employment, with the former bearing the brunt of the current downturn. Except for transportation, blue-collar sectors are down year over year and have been contracting for some time.
Meanwhile, white-collar employment is growing modestly again outside the tech sector.
Labor demand weakens further
The total number of vacancies continues to decline and now stands at around 690,000, roughly 7,000 lower than in the previous month. According to the Office for National Statistics (ONS), the weakening can be attributed to small firms’ hiring decisions or rather the lack thereof. More specifically, slow recruitment is driven by concerns about “labour costs and other economic conditions”. This shows how the policies mentioned above implemented under Labour over the past two years have harmed the labor market.
Unemployment falls, but for the wrong reasons
Given the weakness in job growth and labor demand, you might be surprised to find out that the unemployment rate fell to 4.6% from 4.9% in the previous quarter. Don’t worry — we’re just as astonished as you are. The unemployment rate is measured by a survey of thousands of households. In recent years, the data quality of that survey has declined significantly due to low response rates. In our opinion, the dip reflects a measurement problem rather than a genuine improvement in the labor market.
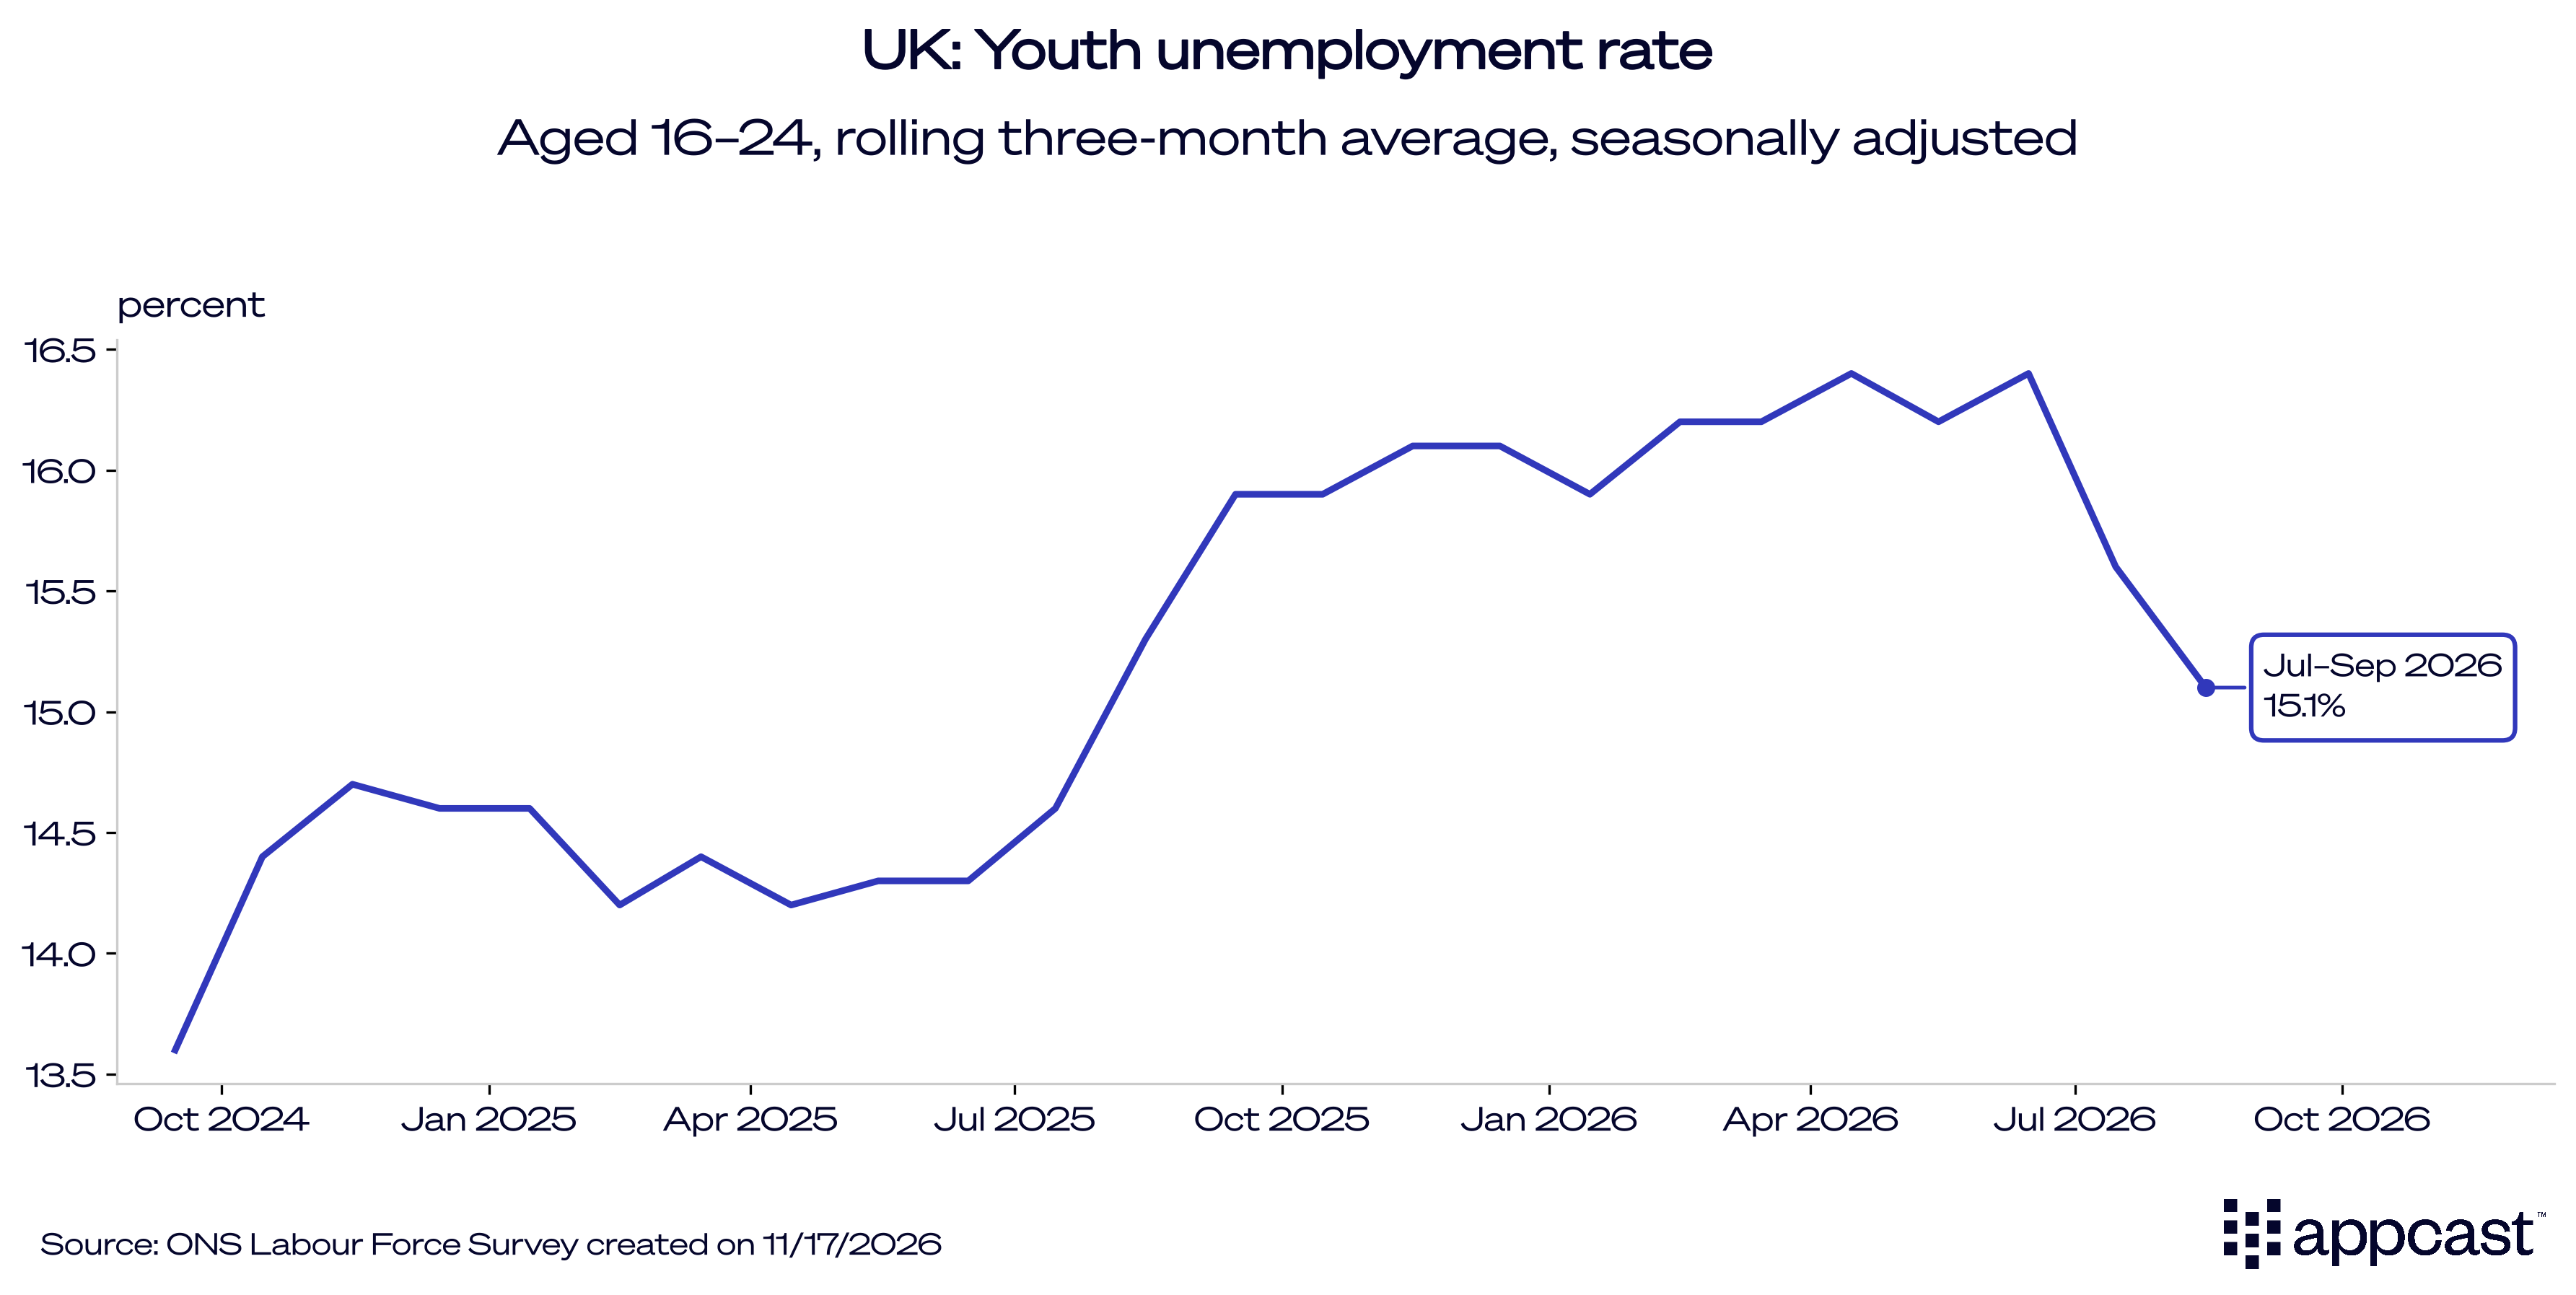
We think so because youth unemployment has fallen by even more, from about 16.4% earlier this summer to 15.1% in the three months to September. But such a strong decline is implausible, especially since job prospects for young people have not really improved.
Labor market data for certain subgroups is even more volatile than aggregate data. The significant decline in youth unemployment can explain about 0.2 percentage points of the decline in the aggregate unemployment rate. But since it is probably a data problem, we should expect both series to mean-revert and head higher again in the months to come. In other words, part of the decline is not real, unfortunately!
Real pay is growing, barely
The ONS’s measure of average weekly earnings is growing at a rate of 3.6%, barely higher than the inflation rate (3.4%), while median pay based on payroll data is growing slightly faster, at more than 4%. But with inflation heading higher in the coming months due to energy prices, real wages will most likely be in negative territory by the first quarter of next year. This is obviously bad news for workers, and it will put a dent in consumption in 2027.
What does this mean for recruiters?
The U.K. labor market continues to underperform. One month of solid data was followed by significant job losses. And even with the potential for positive data revisions, this is not quite a turnaround yet. Job losses continue to be concentrated in blue-collar sectors that have suffered disproportionately from tax and minimum wage hikes. AI hasn’t caused this contraction. But it also hasn’t contributed to any job gains, even as output in tech and professional services has surged this year, leading to much higher-than-expected growth.
For recruiters, all of this means that labor demand continues to be sluggish, especially at smaller companies. This is a bad market for job seekers, as the balance of power has markedly shifted toward employers. While employers can expect to receive a large flow of applicants to any given vacancy, this doesn’t exactly make recruitment easier. That is particularly true as the talent landscape is changing quickly. More and more senior roles across sectors require AI skills, even as part of the workforce has not yet upskilled. Finding the right match therefore remains hard despite an abundance of job seekers.


